Business Tips Archives - Page 7 of 21 - First Class Accounts Ovens and Murray and Busy01 Consulting

Category Archives for "Business Tips"

Should you buy or lease your business assets?

Should you buy or lease your business assets

Should you buy or lease your business assets?

There are certain items of equipment, machinery and hardware that are essential to the operation of your business – whether it’s the delivery van you use to run your home-delivery food service, or the high-end digital printer you use to run your print business.

But when a critical business asset is required, should you buy this item outright, or should you lease the item and pay for it in handy monthly instalments?

To buy or to lease? That is the question

Buying new pieces of business equipment, plant, machinery or vehicles can be an expensive investment. So, depending on your financial situation, it’s important to weigh up the pros and cons of buying, or opting for a leasing option.

First of all, let's look at why you might to decide to buy the item.

Buying: the pros and cons


Pro: It’s a tangible asset

When you buy an item, you own the item outright and it will appear on your balance sheet as one your business assets. As such, by owning these assets outright you increase the perceived capital and value of your business. You can also claim the cost of the asset against your capital allowance for tax purposes.

Pro: It’s yours for the life of the asset 

Once you own the item, you have full use of the equipment for the duration of the life of the asset. Your use of the asset isn’t reliant on you being able to keep up regular lease payments, and if your financial circumstances change then you can sell the asset to free up the capital.

Con: It’s an expensive outlay

Paying for the item up-front is a large outlay for the business and will require you having the cash to cover this cost. Spending a large lump sum in this way may take cash away from other areas of the business, so you need to be 100% sure that this purchase is the right decision and a sound investment.

Con: You may require extra funding

If you don’t have the liquid cash available to buy the item outright, you may need to take out a loan. Asset finance is available from funding providers, but does tie you into a loan agreement that will add to your liabilities as a business – reducing your worth on the balance sheet.

How First Class Accounts Ovens & Murray can help

Our cashflow forecasting services can assist in determining whether you have the financial capacity to make an outright purchase. We can also implement appropriate apps to help you assess the impact on your working capital, ensuring you maintain enough liquidity to cover other business expenses.

Leasing: the pros and cons

Pro: Leasing has a cheaper entry point

If the item you need to purchase has a large price tag, leasing allows you to make use of the asset without the cost of buying it in full. For startups and smaller businesses with minimal capital behind them, this can make leasing a very attractive option. You may not own the asset, but you can make use of it – and this may be the difference between the success or failure of your business.

Pro: You can spread the cost

There is still an associated cost of leasing, but you can spread the cost over a longer period, making it easier to find the necessary liquid cash to meet your lease payments. With this money saved, you can then invest in other areas of the business, helping you to expand, grow and bring in more customers and revenue.

Con: You don’t own the asset

There are different types of leasing agreement. Under a capital lease, you do own the asset (once you’ve paid if off). But if you opt for an operating lease, this is a more short-term lease and you won’t own the asset at the end of the contract. Ownership does have its advantages (including being able to sell off the asset if required) so it’s important to consider what kind of leasing agreement you’re entering into and what the advantages/disadvantages may be.

Con: You may pay more in the long run

Most leasing agreements will attract additional costs and interest on your agreement, so you may well end up paying more than the market price for your asset in the long term. If you can cope with the higher cost, this is fine, but bear in mind that buying outright may have offered greater value.

Con: You may lose the use of the asset

If you can’t keep up your lease payments (due to poor cashflow for example) then the owner of the lease agreement may recall the asset. If this item is crucial to your business model, losing this key asset can have a profound impact on your ability to operate. In this respect, leasing is a more risky prospect, but also an easier option for businesses with less cash to splash.

How First Class Accounts Ovens & Murray can help

Our management accounting services ensure you have timely and accurate financial reports to make informed decisions about leasing versus buying. We can also help you understand your financials, so you can understand if you can meet your financial obligations

How to make the best choice for your business

Deciding whether to buy or lease your equipment isn’t always straightforward. It depends on factors like your financial situation, cash flow, and long-term business goals.

We offer a comprehensive cashflow forecasting and management accounting services to provide you with an accurate picture of your financial future. By implementing the appropriate apps, and with our support, you can review your current financial position, assess your cash flow, and look at your regular costs to help you decide whether buying or leasing is the right thing for the business.

Talk to us about whether buying or leasing is the best way forward.
Key ways to get more from your forecasting

Key ways to get more from your forecasting

Key ways to get more from your forecasting

During challenging times, many businesses see income either disappear completely or drop to dangerous levels.

To be able to navigate the future path of your cashflow, you need to start forecasting, so you can map out your financial position over the coming months and can take the appropriate action to safeguard your cash position.

At First Class Accounts Ovens and Murray, we understand the importance of proactive cashflow management. Our team helps businesses like yours implement effective forecasting tools, ensuring you can monitor your cash position with ease and take timely action when needed.

Forecasting your future cash pipeline

Having access to detailed forecasts helps you to scenario-plan, search for cost-savings and look for strategies that will preserve your cashflow position.

Remaining in control of the cash coming into (and going out of) the business is the real focus, so you can accurately predict your financial position and can resolve any issues.

Our team provides customised forecasting services, allowing you to see the full picture of your cashflow pipeline. We help you stay in control, so you can confidently manage both the inflow and outflow of cash.

Key ways to get more from your forecasting

Run regular forecasts

The financial landscape is changing on a daily basis at present. A cashflow forecast is not a document that remains static. Variables and external drivers are literally changing each day, so it’s vital that you run frequent forecasts and react swiftly to any projected cash issues as they become apparent.

Use the latest cashflow forecasting apps 

Cashflow forecasting apps, like Futrli, integrate with your Xero accounts, giving a drilled-down view of how your cash inflows and outflows will pan out over the coming months – information that will inform and justify the decisions you make during these extremely challenging times.

At First Class Accounts Ovens and Murray, we specialise in integrating the latest forecasting tools with your accounting software. Our team can show you how to use apps like Futrli to get detailed insights into your cashflow, so you can make informed decisions based on real-time data

Explore the right revenue streams

Most sectors will have seen their face-to-face sales drop to absolute zero since quarantine restrictions came into place. To overcome this, there’s a real imperative to explore revenue streams and new opportunities for income. An example of this is coffee shops that now sell roasted beans online (this will depend on lockdown restrictions). The idea is to find ways to increase the money that’s coming in the door and balance out your unavoidable expenses.

Get proactive with cost-cutting

If you can reduce cash outflows to a minimum, that will have a real impact on the health of your future cashflow. Pare back your operations and aim to reduce things like unnecessary software subscriptions, or over-ordering of basic supplies. Negotiating cheaper rates with suppliers, if possible, will also help.

Review your staffing needs

Now’s not the time to make anyone redundant, but you can look at ways to reduce the costs of staffing and resourcing. Reducing working hours or redeploying staff in different roles are all options that reduce payroll costs, while also looking after your staff’s welfare.

Run a variety of scenarios

Changing the financial drivers in your forecast model allows you to scenario-plan different strategies and options. Many of these will be in a long-term plan when restrictions ease. Scenario-planning lets you answer questions and will give you some hard evidence on which to base your decision-making and strategic outlook over the coming months.

Look at various ways to access funding

If forecasts show a giant cashflow hole coming up, you’re going to need additional funding to get through this crisis. We can assist your business to investigate funding opportunities from grants, banks, loan providers, alternative lenders and crowd-sourcing funders.

Forecasting is an important step to give you the business intelligence to support your decision making. 

By working with First Class Accounts Ovens and Murray, you’ll have the tools, insights, and ongoing support to ensure your cashflow forecasts are accurate and responsive to your needs.

Talk to us about setting up cashflow forecasting today. We’re here to help you stay in control of your financial future. Get in touch today.

The Importance of Reviewing Your Financial Reports

The Importance of Reviewing Your Financial Reports

The Importance of Reviewing Your Financial Reports

Understanding your financial reports is essential for the health and success of your business.

At First Class Accounts Ovens and Murray, we believe that taking the time to review these reports regularly is a key part of effective business management. 

Whether you’re managing your finances yourself or working with a bookkeeper, here’s why you should make financial reports a priority.

1. Profit and Loss Report (P&L): Understanding Your Business’s Performance

The Profit and Loss report provides a detailed overview of your business’s financial performance over a specific period. It shows your revenue minus expenses, giving you a clear picture of your profitability.

Why It’s Important:
Regularly reviewing your P&L allows you to monitor your business’s financial health month by month. It helps you understand what drives your profits and highlights areas that may need attention.

Comparing different periods can reveal trends and pinpoint any anomalies, ensuring that you stay on top of your financial situation.

2. Balance Sheet: Assessing Your Financial Position

The Balance Sheet is a snapshot of your business’s financial position at a given point in time. It details your Assets, Liabilities, and Equity, providing insight into what your business owns and owes.

Why It’s Important:
Your Balance Sheet, when reviewed alongside your P&L, offers a comprehensive view of your financial standing. This report is crucial when applying for loans or assessing the overall health of your business.

Working with a bookkeeper can help ensure that you fully understand your Balance Sheet, allowing you to make informed financial decisions.

3. Accounts Receivable Ageing Report: Managing Your Invoices

The Accounts Receivable Ageing Report shows how much money is owed to your business, broken down by how overdue these payments are. It’s an essential tool for managing your incoming cash flow.

Why It’s Important:
By staying on top of your receivables, you can ensure that overdue accounts are followed up promptly, reducing the risk of bad debts. This report is vital for maintaining a steady cash flow, which is the lifeblood of any business.

4. Accounts Payable Ageing Report: Keeping Track of What You Owe

The Accounts Payable Ageing Report details the money your business owes to suppliers, segmented by how overdue the payments are. This report helps you manage your outgoing cash flow.

Why It’s Important:
Maintaining good relationships with your suppliers is crucial, and timely payments are a big part of that. Reviewing your Aged Payables ensures that you meet your obligations on time, preserving those essential business relationships.

 A bookkeeper can help you keep your Accounts Payable organised and up to date.

5. Cash Flow Management: Ensuring Financial Stability

Effective cash flow management relies on a clear understanding of both your Accounts Receivable and Payable. Together with your P&L and Balance Sheet, these reports help you plan for the future and avoid financial pitfalls.

Why It’s Important:
Knowing when money is coming in and going out allows you to plan better, ensuring that your business has the funds it needs when it needs them. This level of financial awareness is crucial for sustaining operations and pursuing growth opportunities.

Your bookkeeper can assist in creating cash flow forecasts that align with your business goals.

6. Informed Decision Making: Empowering Your Business

Your financial reports collectively tell the story of your business. Understanding this story empowers you to make decisions that positively impact your profitability and long-term viability.

Why It’s Important:
The better you understand your financial reports, the more confident you’ll be in making strategic decisions. Whether it’s cutting costs, investing in new opportunities, or planning for growth, having accurate financial data at your fingertips is essential.

Partner with First Class Accounts Ovens and Murray

At First Class Accounts Ovens and Murray, we’re here to help you make sense of your financial reports. Whether you need help understanding your P&L, Balance Sheet, or cash flow, our experienced bookkeepers are ready to assist.

We’ll work with you to ensure that your financial records are accurate and up to date, giving you the confidence to make informed business decisions. Get in touch.

Supercharge Your Business with these ten tips

Supercharge your business

Supercharge Your Business: Proven Strategies for Success

Maintaining momentum and driving growth can be challenging. However, with the right strategies in place, you can supercharge your business and achieve remarkable results. 

Here are ten practical tips to help you navigate each business quarter with purpose, vision, and the courage to elevate your business to new heights.

1. Use Technology

Embrace technology to streamline administrative tasks, enhance communication, and improve reporting and accountability. Utilise the best apps to reduce paperwork and automate processes where possible.

Research and implement software solutions that cater to your specific business needs, such as project management tools, CRM systems, and accounting software. Stay updated with technological advancements and continually seek ways to integrate them into your operations.

At First Class Accounts Ovens & Murray and Busy01 Consulting, we can help your business by integrating the most effective apps tailored to your needs. 

2. Eliminate Distractions

Time is the most precious resource for any business. Many owners find themselves bogged down by distractions and focusing on non-essential tasks. To combat this, be decisive. Reduce standard meeting times, cut down on unnecessary administrative tasks, and delegate whenever possible. By doing so, you'll create more time to focus on what truly matters.

Implementing productivity tools like time-tracking apps can help you identify and eliminate time-wasting activities. Additionally, consider setting specific times for checking emails and notifications to avoid constant interruptions. Creating a daily or weekly priority list can also keep you on track and ensure that you're focusing on high-impact tasks.

3. Say Goodbye to Bad Customers

Some customers may drain your resources without providing significant value in return. If feasible, identify and phase out ten time-wasters, late payers, or troublesome clients. This will not only relieve stress but also allow you to allocate your resources more effectively.

Conduct a customer analysis to identify which clients are profitable and which ones are not. Use metrics such as customer lifetime value (CLV) and customer acquisition cost (CAC) to make informed decisions. By focusing on high-value customers, you can improve your overall profitability and customer satisfaction.

4. Invest More

With the time and mental space gained from the first two steps, allocate resources—time, key personnel, and money—toward strategic initiatives. Passionately redeploy these resources to drive significant improvements in your business.

Consider investing in employee training and development programs to enhance their skills and productivity. Explore opportunities for upgrading your equipment or expanding your product line to meet market demands. These investments can lead to long-term growth and a competitive edge.

5. Get a Plan

Operating without a plan is like embarking on a journey without a map. Develop a robust planning process, create a comprehensive business plan, and ensure its execution.

Include measurable goals and timelines in your plan to track progress effectively. Regularly review and adjust your plan based on market changes and business performance. Incorporate contingency plans to address potential risks and uncertainties.

6. Reconfigure

Don’t let unmotivated or incompatible employees hold you back. If someone isn't a good fit, consider parting ways to free up their future and make room for someone who aligns better with your business goals.

Implement regular performance reviews and provide constructive feedback to help employees improve. Offer opportunities for skill development and career advancement to retain top talent. A positive and motivated team can significantly impact your business success.

7. Value Add

Avoid stagnation by focusing on activities that add value. Aim to make a meaningful impact through your work, ensuring that it brings real value and significance to your clients.

Engage with your customers to understand their needs and preferences. Develop new products or services that address their pain points and exceed their expectations. Consistently delivering value can lead to increased customer loyalty and referrals.

8. Be Different

Stand out from the competition by positioning yourself as unique. Attract ambitious, growing, and engaged clients and employees by breaking the mould.

Identify your unique selling propositions (USPs) and highlight them in your marketing efforts. Foster a culture of innovation and encourage your team to think creatively. Differentiate yourself through exceptional customer service and a strong brand identity.

9. Deploy Marketing

Develop a straightforward marketing plan to enhance your reach and market penetration. Dedicate a percentage of your revenue to marketing efforts and ensure online engagement is a core component.

Leverage digital marketing strategies such as SEO, social media marketing, and email campaigns to reach a broader audience. Monitor and analyse your marketing performance to identify areas for improvement and maximise your return on investment.

10. Ask for Referrals

Actively seek out referral relationships to attract high-quality customers. Networking and word-of-mouth can be powerful tools in driving business growth.

Establish a referral program that rewards customers for referring new clients. Build strong relationships with complementary businesses and explore partnership opportunities. Regularly request feedback from your clients to ensure their satisfaction and encourage referrals.

Supercharge your business

By implementing these ten tips, you can supercharge your business and achieve sustainable growth. Stay focused, be proactive, and continuously seek ways to improve and innovate.

Ready to take your business to the next level? 

At First Class Accounts Ovens & Murray, we provide tailored bookkeeping, payroll and advisory services to help you implement these strategies effectively. Contact us today to learn how we can support your journey to success and supercharge your business!

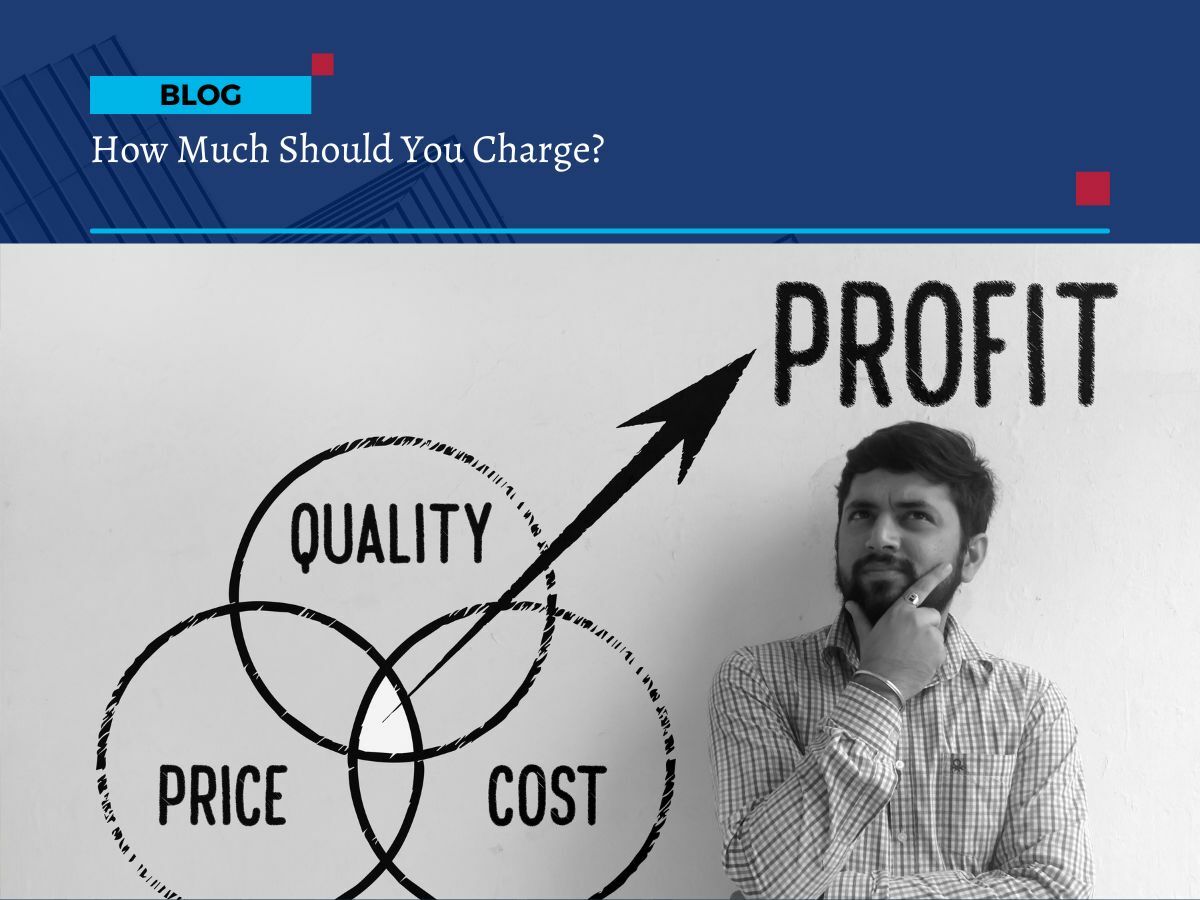
How Much Should You Charge?

How much should you charge

How Much Should You Charge?

Getting your pricing right is one of the best ways to plan for business success, but how do you know how much you should charge?

First, don’t make a rushed decision; take the time to properly understand the market, your total costs, and how to position your products or services.

Figuring out how much to charge is a big learning curve for any business owner. The answer to how to approach it will fluctuate as circumstances and markets change. It is important to revisit the question throughout the lifecycle of your business.

There is No Magic Formula

All businesses are unique, with an individual offering of products and services. Before you set your pricing, it’s important to look at the whole picture. This will help to ensure you are being strategic and not just following trends.

Gather the Data

To get started, you need to gather as much information as possible. Block out some time to sit down with your business data and strategies. Pricing is essentially figuring out where your products and services are positioned in the market. So keep your business strategies top of mind. It doesn’t have to be a confusing exercise. Just grab a coffee and get started.

Here Are the First Steps to Consider:

1. Record All the Costs Involved in Production

Start by listing all direct and indirect costs associated with your product or service. Direct costs include materials, labour, and production expenses. Indirect costs encompass assets, insurance, licences, and legal fees. This comprehensive list ensures you don't overlook any expenses that could affect your pricing strategy.

2. Consider Your Current Profit Margin or Required Margin

Once you have your total costs, think about your profit margin. Understand the difference between net and gross profit margins. Gross profit margin is the difference between sales and the cost of goods sold, while net profit margin accounts for all operating expenses. Decide what margin is necessary for your business to be sustainable and profitable.

3. Conduct Thorough Competitor Research

Research your competitors thoroughly. Understand the market landscape and what others are charging for similar products or services. Identify your unique selling points (USPs) that allow you to differentiate your pricing. This research helps you position your offerings competitively without underpricing or overpricing.

4. Evaluate Your Offerings

Assess the value-added aspects of your products or services. Consider where your offerings fall on the spectrum from cheap and no-frills to high-end premium. Can you create a range of products at different price points to cater to various segments of the market? This strategy can help you attract a broader customer base.

Revisit and Adjust Your Pricing Regularly

Market conditions and business circumstances are always changing. Regularly reviewing and adjusting your pricing ensures that you stay competitive and meet your customers' expectations. This proactive approach helps you maintain profitability and growth.

Additional Considerations

Understanding Customer Perception

How customers perceive your pricing can significantly impact your sales. If your prices are too low, customers might question the quality of your products. Conversely, if your prices are too high without justifiable reasons, you might drive potential customers away. Balancing perception with reality is key to effective pricing.

Value-Based Pricing

Value-based pricing involves setting prices based on the perceived value to the customer rather than the cost of production. This method requires a deep understanding of your customers' needs and how much they are willing to pay for the benefits your product or service provides. Value-based pricing can often lead to higher profit margins.

Psychological Pricing

Psychological pricing strategies, such as setting prices just below a round number (e.g., $9.99 instead of $10), can influence customers' buying decisions. This tactic can make prices seem lower than they actually are, potentially increasing sales.

Discounts and Promotions

Strategically use discounts and promotions to attract customers and boost sales. However, be careful not to rely too heavily on these tactics, as they can devalue your product and create an expectation for lower prices. Use them sparingly and strategically to drive short-term sales and customer acquisition.

Stay Ahead of the Game

Determining how much to charge for your products or services is a crucial aspect of running a successful business. By thoroughly understanding your costs, profit margins, market conditions, and customer perceptions, you can develop a pricing strategy that supports your business goals. Remember, pricing is not a one-time decision but an ongoing process that requires regular review and adjustment.

For more personalised assistance in developing a pricing strategy tailored to your business needs, contact us at First Class Accounts Ovens & Murray and Busy01 Consulting. We're here to help you navigate the complexities of pricing and achieve long-term business success.

Business Strategy

Get strategy at the heart of your successful business

Get strategy at the heart of your successful business


Putting strategy at the heart of your business activity should give you greater direction and focus and lead to stimulating, profitable opportunities. A well-thought-out strategy is crucial for navigating challenges and capitalising on opportunities.

Businesses that have clear objectives or goals, robust accountability, and a shared sense of purpose should always outperform those that just show up and go through the motions. This focused approach ensures that all efforts are aligned towards achieving common goals, thereby maximising efficiency and effectiveness.

The Importance of a Strategic Plan

Strategy lies at the heart of most successful businesses. 

To achieve this, you need to resource and execute with purpose. Unfortunately, few businesses have a strategic plan or a robust planning process. 

Changing this situation should be a top priority. A strategic plan not only provides a roadmap for your business but also helps in anticipating challenges and preparing for them.

Business Strategy Tips for Business Owners

To help you get started, here are two top tips for putting strategy at the heart of your business success.

1. Process Creates the Plan

Getting strategy at the heart of your success will require you to carve out some time, get a process started, and shake things up. There’s no better time to review and tweak your business model, future-proof compelling services, and get your strategic building blocks in place.

Just as every good strategy has key elements, every good plan needs a step-by-step process. In fact, the process is often just as important as the plan itself. 

A strategic planning retreat with your core team is a great way to start the process – find a spot offsite to get the creative juices flowing such as a beach, a park, or a vineyard, and set an agenda.

2. Key Elements of an Effective Strategy

The key elements in a good strategy normally incorporate:

  • Vision: This is a statement that identifies what a company would like to achieve or accomplish. A clear vision provides direction and inspiration, helping to align all members of the organisation towards common goals.

  • Values: These are the fundamental beliefs upon which your business and its behaviour are based. They are the guiding principles that your business uses to manage its internal affairs as well as its relationship with customers. Strong values build a solid foundation for organisational culture and decision-making.

  • Objectives: These should be SMART (specific, measurable, achievable, realistic, and timebound). Having both short-term and long-term objectives ensures that your business stays on track and can measure its progress effectively.

  • KPIs: Key Performance Indicators are measurable values that demonstrate how effectively a company is achieving key business objectives. KPIs help in monitoring performance and making informed decisions.

  • Actions: These outline what needs to be done to meet the objectives. Make this simple and clear to ensure that all team members understand their roles and responsibilities.

  • Owners: Delegating tasks to specific owners ensures follow-through and accountability. Assigning ownership of tasks helps in tracking progress and maintaining responsibility.

  • Deadlines: Setting deadlines for when your actions will be complete ensures you make progress. Deadlines provide a sense of urgency and help in prioritising tasks.

It doesn’t need to be much more complicated than that, but do invest the time and effort in doing this right. 

A proactive, value-add strategic model will need fresh thinking, debate, research, and open conversations. Enjoy and embrace the process, and you should end up with a good outcome.

Implementing Your Strategy

Implementing a strategic plan requires commitment and consistent effort. Here are some additional steps to ensure successful implementation:

  • Communication: Clearly communicate the strategy to all members of the organisation. Ensure everyone understands their role in achieving the strategic objectives.

  • Monitoring and Evaluation: Regularly monitor progress against the set objectives and KPIs. Evaluate the effectiveness of your strategy and make adjustments as necessary.

  • Flexibility: Be prepared to adapt your strategy in response to changes in the business environment. Flexibility is key to maintaining relevance and achieving long-term success.

  • Continuous Improvement: Foster a culture of continuous improvement within your organisation. Encourage feedback and use it to refine your strategy and processes.

Seeking Professional Guidance

Great planning requires a guide, facilitator, and/or professional expertise to be as robust as possible. We can help your business and guide you through the steps. Professional guidance can provide valuable insights and ensure that your strategic plan is comprehensive and effective.

Putting strategy at the heart of your business activity should not only give your business greater direction and focus but also lead to stimulating, profitable opportunities. 

It’s time to get started on creating a strategic plan that will drive your business towards long-term success. By following these steps and seeking professional assistance when needed, you can build a solid foundation for your business and achieve your strategic goals.

Talk to us about how we can support your business strategy and help you achieve your objectives. 

Remote work in 2024

Remote work in 2024

Remote Work in 2024: Adapting to the New Normal


Remote work has significantly evolved over the past five years, becoming a mainstay for many businesses.

Back in 2019, we discussed the rising trend of remote work in our blog "Remote Work is on the Rise". As we move further into 2024, it’s clear that remote work is no longer a temporary solution but a permanent fixture in the way we operate.

The benefits of remote work in 2024

Attracting and Retaining Talent

Remote work opens the door to a global talent pool. You're no longer restricted to hiring within your local area or requiring employees to relocate. This flexibility is a major draw for top talent who value work-life balance.

Increased Productivity

Many studies have shown that remote workers often achieve higher productivity levels than their in-office counterparts.

For example, a study by Great Place to Work found that remote work increased productivity by 13% during the pandemic (Great Place To Work®). Additionally, research from McKinsey indicated that flexible working arrangements have significantly boosted employee satisfaction and productivity (McKinsey & Company).

Cost Savings: Both employers and employees can save money. Businesses can reduce overhead costs related to maintaining physical office spaces, while employees save on commuting expenses. According to Business News Daily, remote workers also experience less stress, contributing to increased productivity (Business News Daily).

The Benefits of Outsourcing Bookkeeping and Payroll to Remote-Capable Organisations


Outsourcing bookkeeping and payroll to firms that excel in remote work, like Busy01 Consulting and First Class Accounts Ovens & Murray, offers several advantages:

Consistency

Services are unaffected by location or employee absences. With remote teams, firms like Busy01 and FCA ensure that your bookkeeping and payroll tasks are completed on time, every time.

Expertise

Access to a team of experts who are well-versed in the latest technologies and best practices, ensuring compliance and efficiency.

Focus on Core Activities

As a business, you can focus on your core competencies while leaving the complex and time-consuming tasks of bookkeeping and payroll to professionals.

Scalability

Easily scale services up or down depending on your business needs without the hassle of hiring and training new staff.

Security and Data Protection

With the increase in remote work, data security has become a top priority. Businesses must ensure that their remote work policies include robust cybersecurity measures. This includes using VPNs, secure cloud services, and regular training on data protection practices.

At Busy01 and First Class Accounts (FCA), we emphasise the importance of maintaining high security standards to protect sensitive business data. For more detailed information on cyber security, you can refer to our blog, here.

Preparing Your Business for Remote Work in 2024

Establish Clear Communication Channels

Strong communication is vital for remote teams. Ensure you have multiple channels for different types of communication:

  • Instant Messaging: Tools like Slack for quick, informal communication.
  • Video Conferencing: Regular video calls via platforms like Zoom to maintain face-to-face interaction.
  • Project Management: Software like Trello or Asana to keep track of tasks and deadlines.

Invest in Technology

Provide your remote employees with the necessary technology:

  • Hardware: Laptops, monitors, and other required devices.
  • Software: Subscriptions to essential tools and applications.
  • Support: Technical support to assist with any issues that arise.

Foster a Positive Remote Work Culture

Building and maintaining a positive work culture is crucial. Encourage regular team-building activities, virtual social events, and ensure managers are trained to support remote employees effectively.

Address Tax and Legal Considerations

Remote work can have tax implications. Make sure you are aware of the regulations in your area and seek advice to ensure compliance. This includes understanding how remote work affects payroll, benefits, and other legal aspects.

Embrace the Future of Work

Remote work in 2024 is more refined and ingrained in our work culture than ever before. By focusing on robust communication, mental health, security, and the right technology, businesses can thrive in this remote-first world.

If you’re considering or expanding remote work for your team, contact us to ensure your systems are up to date and you’re compliant with all necessary regulations.

How to exit your business

Getting ready to exit your business

Getting ready to exit your business

Selling your business is a significant milestone that requires careful planning and strategic preparation. 

To ensure you get the best possible return on your investment, it's crucial to have a solid exit strategy in place. At First Class Accounts Ovens & Murray and Busy01 Consulting, we specialise in helping business owners develop and implement effective exit plans.

When you sell up, you want your business to have as much inherent value as possible – so you get a good price, a great return on your investment and the best possible payout.

So, how do you take yourself ‘out of the business’ as the founder, add the best value and set up an effective and financially beneficial exit strategy?

Exit your business - add value to your company

Whether the goal of your five-year plan is an acquisition by a larger corporate, or selling your share of the company to a chosen successor, it’s critically important to focus on adding value.

The more attractive the business looks in the market, the better the price you’ll achieve, or the better the yield you’ll see on selling your company shares.

To drive that value:

Work on the business, not in it

Working on the business means you’re no longer a fundamental part of the day-to-day operations and can focus on the higher-level strategic elements. 

This means building a strong management team and delegating responsibilities effectively. It also involves creating systems and processes that allow the business to run smoothly without your constant involvement. 

By doing this, you enhance the business's attractiveness to potential buyers, who will see a well-organised, self-sufficient operation.

Invest in adding value

Keep profits in the business, reduce your personal drawings, and plough that money back into growth and investment. This might include upgrading equipment, expanding your product line, improving your online presence, or enhancing customer service. 

By continuously reinvesting in your business, you not only boost its current value but also make it more attractive to potential buyers.

Improve your financial health

By taking control of your finances and building a strong balance sheet, positive cash flow, and attractive profit forecasts, you make your business more appealing to buyers. 

This includes maintaining accurate and up-to-date financial records, managing debt effectively, and ensuring that your financial statements reflect the true value of your business. 

A business with healthy finances is more likely to attract serious buyers and command a higher sale price.

Have a proper exit strategy

Develop a plan that has agreed targets, so you can track and measure whether goals are hit, and a strategy your team can get behind. 

Your exit strategy should include identifying potential buyers, understanding the market value of your business, and setting a timeline for the sale. It’s also crucial to consider the tax implications of selling your business and to plan accordingly to maximise your post-sale benefits. 

Make sure your team is aligned with this plan to ensure a smooth transition.

Talk to us about exiting your business

If you’re looking to sell up, you need a plan. Come and talk to us about creating a workable exit strategy, with a clear focus on driving value and delivering a solid return on your investment.

Get in touch to build your exit strategy.

Selling your business is a major decision that requires careful planning and expert advice. At First Class Accounts Ovens & Murray and Busy01 Consulting, we are here to help you every step of the way. Contact us today to discuss how we can assist you in creating a comprehensive exit strategy that ensures you get the best possible return on your investment.

Make better business decisions

Make better business decisions

Make better business decisions

As a business owner, you want to make the best possible decisions for your business. The choices you make regarding strategy, spending, revenue generation and cashflow management can all have a major impact on the long-term future of the company.

So, how do you give yourself that competitive edge when it comes to decision-making?

The answer is to make the most of your financial data and to use the outputs from today’s cloud accounting tools and finance apps to inform and guide your choices as a leader.

Five major benefits of having financial real-time data

Cloud accounting has revolutionised the ways that small business owners manage their business accounts and broader financial management.

With the right tech stack and cloud accounting software, it’s possible to have genuine real-time information about your business finances. That instant access to your financial performance numbers is a game-changer, for a number of reasons.

Here are five ways that deep financial data can help to drive your business success...

Real-time data gives you:

1. Informed decision-making

With access to the most up-to-date financial data, you’re no longer flying blind! Real-time data empowers you to make strategic decisions based on the most current business information. You can see how marketing budgets are performing, analyse your sales trends and identify areas for cost-cutting – with a dashboard that provides a real-time snapshot of your overall financial health. You’re informed, on the ball and can react like lightning to any pressing business opportunities, or unplanned threats to your funding and operating cashflow.

2. Improved cashflow management

Cash is king, so it’s crucial that you have the best possible insights into your cashflow position, planning and management. Real-time cash data helps you plan for upcoming expenses, predict potential shortfalls and make informed decisions about borrowing or investment strategies. This real-time visibility ensures you always have sufficient funds to cover your operational costs, dodging the cashflow pitfalls that could otherwise hinder your business growth.

3. Enhanced budgeting and forecasting

You can ditch the static spreadsheets and embrace a more dynamic, real-time way to run your budgeting and forecasting. Track your progress towards financial goals, identify variances and deviations from key budgets, and adjust your plans and strategy accordingly. Accurate historic and real-time data also means more accurate forecasts, leading to better resource allocation and improved financial planning for the future.

4. Increased potential to turn a profit

With access to real-time data, finding the prime areas for cost reduction and revenue optimisation is made easy. You can quickly hone in on the products that are bringing in the biggest sales revenues, or the operational expenses that are costing you money but failing to deliver a healthy return on investment (ROI). If the majority of your sales income is coming from one product, by tracking key metrics like customer acquisition costs and conversion rates, you can identify and refine marketing strategies to maximise return on investment. Additionally, real-time sales data allows you to react quickly to customer trends and adjust pricing strategies to improve profitability.

5. Greater confidence in your business potential 

Modern accounting tech puts all this real-time data right at your fingertips, so you always feel in control of your finances. That’s a major boost to your confidence as a business owner, giving you the overview and insights you need to keep a tight grip on your financial health. Having this transparency makes it possible to share key metrics with your key stakeholders, like investors or partners. It also demonstrates your commitment to keeping good records and focusing on your financial management – a trait that investors, lenders and banks will see as a good sign of the viability of your business.

Talk to us about accessing your finance data goldmine

If you’re currently only tracking the most basic of finance metrics, now’s the time to dive deeper into your pool of valuable financial data. The more detailed and refined your finance dashboard becomes, the more you’re in control of the next steps of your business.

We can help you set up a tailored business dashboard and management reporting tools to track all the most valuable finance metrics for your business.

Get in touch to start exploring your real-time data

1 … 5 6 7 8 9 … 21