Renae Pitargue, Author at First Class Accounts Ovens and Murray and Busy01 Consulting - Page 13 of 34

All Posts by Renae Pitargue

How to use forecasts and scenario-planning

How to use forecasts and scenario-planning

How to use forecasts and scenario-planning

For centuries, accounting was all about reviewing historic information – but that only told you about the past, not what was going to happen in the future.

If you’re only looking back at past periods and historic numbers, that limits the insights you can achieve into your business. With a backward-looking ideology, it becomes difficult to plan, run through different scenarios or understand the path of the business.

Forecasting changes this. With the right data analysis and forecasting tools, you can project sales, cash, revenue and profits into the future – and get in control of your business.

At First Class Accounts Ovens & Murray, we understand that your business is dynamic, constantly evolving, and influenced by countless factors. We specialise in implementing forecasting apps, such as Futrli, that allow you to see beyond the numbers and into the future of your business. 

Our bookkeeping and app implementation expertise helps ensure that you’re using up-to-date, accurate data when forecasting, giving you confidence in the decisions you make.

A forward-looking view of your business journey

Forecasting switches the focus of your financial management. By moving to a forward-looking view of your business journey, you can see further down the road – and that helps to spot the opportunities and avoid the common business pitfalls.

By collaborating closely with you, our team at First Class Accounts Ovens and Murray can implement Futurli, or alternative forecasting apps to help you analyse trends, identify patterns, and anticipate challenges ahead of time. Our goal is to provide you with a clearer picture of what’s coming, so you can focus on making strategic decisions to grow your business. Whether it's sales, cash flow, or profit forecasting, our team is here to help you take charge of the future.

Forecasting adds value by:

Highlighting the data patterns

A forecasting tool takes your historic data and projects it forward in time. This helps you and your advisers to spot the patterns, trends, gaps and opportunities, revealing the true ‘story’ behind your business accounts. For example, forecasting may reveal a predicted seasonal slump in the next quarter, allowing you to plan ahead and proactively take action to minimise any negative impact.

Giving you a future view of your business

Instinctively, business owners will look back at prior periods to assess performance. There’s value to reviewing your historic actuals, of course, but using forecasting helps you to look forward, rather than just backwards. Forecasting is the satnav, showing you the road ahead, rather than the rear-view mirror showing you the road you’ve already travelled.

At First Class Accounts Ovens and Murray we make it easy to access this future view by integrating apps that generate future financial projections with just a few clicks.  This gives you a clear understanding of what’s next for your business, enabling you to allocate resources more effectively, plan for growth, and avoid potential pitfalls. 

Helping you scenario-plan

With a financial model of your key drivers, combined with accurate forecasting, you can quick answer your burning ‘What if…?’ questions.

Forecasting lets you run different scenarios, with different drivers, to see how business decisions may pan out over time. If option B performs better than option A, that’s invaluable information when defining your next strategic move.

Making informed, evidence-based decisions

Having ‘the full picture’ of combined historic numbers, forecasts and longer-term projections aides your business decision-making. Forecasting gives you solid evidence on which to base your strategy, and helps to red flag any threats that are looming on the horizon – giving you the best possible information to keep your executive team informed and on the ball.

We believe in making decisions based on evidence, not guesswork. That’s why implementing the appropriate apps can provide you with the data you need to inform your strategies. We ensure that your forecasts are based on accurate, up-to-date financial information, helping you make better decisions. Whether it's managing cash flow or planning for future growth, we give you the tools to act with confidence.

A deeper relationship with your accountant

Forecasting also helps us to get a far more granular view of your business. This helps to spot potential areas of performance improvement, and to give you the best possible strategic advice, all backed up by solid, empirical data and management information.

Take Control of Your Future with Forecasting

If you want to get in control of the destiny of your company, come and talk to us. Forecasting helps you highlight your future threats and opportunities – and create a proactive strategy to improve the performance of your business.

At First Class Accounts Ovens & Murray, we not only manage your bookkeeping but also help you implement powerful forecasting tools like Futrli. By connecting this app with your Xero platform, we can give you clear insights into what lies ahead. 

Our goal is to help you plan for the future, whether that involves managing cash flow, preparing for growth, or navigating uncertain markets. Whether you’re looking to grow your business, manage cash flow more effectively, or simply get a better sense of what’s coming, we provide the tools and insights you need to succeed.
Talk to us today to learn more about how forecasting can benefit your business and set you on the path to future success.

The Importance of Reviewing Your Financial Reports

The Importance of Reviewing Your Financial Reports

The Importance of Reviewing Your Financial Reports

Understanding your financial reports is essential for the health and success of your business.

At First Class Accounts Ovens and Murray, we believe that taking the time to review these reports regularly is a key part of effective business management. 

Whether you’re managing your finances yourself or working with a bookkeeper, here’s why you should make financial reports a priority.

1. Profit and Loss Report (P&L): Understanding Your Business’s Performance

The Profit and Loss report provides a detailed overview of your business’s financial performance over a specific period. It shows your revenue minus expenses, giving you a clear picture of your profitability.

Why It’s Important:
Regularly reviewing your P&L allows you to monitor your business’s financial health month by month. It helps you understand what drives your profits and highlights areas that may need attention.

Comparing different periods can reveal trends and pinpoint any anomalies, ensuring that you stay on top of your financial situation.

2. Balance Sheet: Assessing Your Financial Position

The Balance Sheet is a snapshot of your business’s financial position at a given point in time. It details your Assets, Liabilities, and Equity, providing insight into what your business owns and owes.

Why It’s Important:
Your Balance Sheet, when reviewed alongside your P&L, offers a comprehensive view of your financial standing. This report is crucial when applying for loans or assessing the overall health of your business.

Working with a bookkeeper can help ensure that you fully understand your Balance Sheet, allowing you to make informed financial decisions.

3. Accounts Receivable Ageing Report: Managing Your Invoices

The Accounts Receivable Ageing Report shows how much money is owed to your business, broken down by how overdue these payments are. It’s an essential tool for managing your incoming cash flow.

Why It’s Important:
By staying on top of your receivables, you can ensure that overdue accounts are followed up promptly, reducing the risk of bad debts. This report is vital for maintaining a steady cash flow, which is the lifeblood of any business.

4. Accounts Payable Ageing Report: Keeping Track of What You Owe

The Accounts Payable Ageing Report details the money your business owes to suppliers, segmented by how overdue the payments are. This report helps you manage your outgoing cash flow.

Why It’s Important:
Maintaining good relationships with your suppliers is crucial, and timely payments are a big part of that. Reviewing your Aged Payables ensures that you meet your obligations on time, preserving those essential business relationships.

 A bookkeeper can help you keep your Accounts Payable organised and up to date.

5. Cash Flow Management: Ensuring Financial Stability

Effective cash flow management relies on a clear understanding of both your Accounts Receivable and Payable. Together with your P&L and Balance Sheet, these reports help you plan for the future and avoid financial pitfalls.

Why It’s Important:
Knowing when money is coming in and going out allows you to plan better, ensuring that your business has the funds it needs when it needs them. This level of financial awareness is crucial for sustaining operations and pursuing growth opportunities.

Your bookkeeper can assist in creating cash flow forecasts that align with your business goals.

6. Informed Decision Making: Empowering Your Business

Your financial reports collectively tell the story of your business. Understanding this story empowers you to make decisions that positively impact your profitability and long-term viability.

Why It’s Important:
The better you understand your financial reports, the more confident you’ll be in making strategic decisions. Whether it’s cutting costs, investing in new opportunities, or planning for growth, having accurate financial data at your fingertips is essential.

Partner with First Class Accounts Ovens and Murray

At First Class Accounts Ovens and Murray, we’re here to help you make sense of your financial reports. Whether you need help understanding your P&L, Balance Sheet, or cash flow, our experienced bookkeepers are ready to assist.

We’ll work with you to ensure that your financial records are accurate and up to date, giving you the confidence to make informed business decisions. Get in touch.

Following Up Invoices in a Challenging Economy

Following Up Invoices in a Challenging Economy

Following Up Invoices in a Challenging Economy

In times when the economy is down, it can feel particularly challenging to chase up payment of invoices. Yet, keeping cash flowing into your business is crucial to cover expenses and meet your obligations to others. 

While the task might seem daunting, maintaining a steady cash flow is essential to your business's survival and growth. 

As with all dealings in difficult times, a combination of empathy and open communication can significantly improve your chances of receiving timely payments without damaging customer relationships.

The following tips are useful to keep in mind when asking for payment. 

The Importance of Personalised Communication

Connecting with your customers is important. Try to make it personal to their situation rather than a one-size-fits-all email. Connecting on a more personal level shows you value them and are conscious of the impacts that the current situation may be having on them. The empathy you show now will also be remembered when the economy recovers. Be proactive—early communication will help you stay on top of cash flow and will also alert you if you need to account for late payments.

When reaching out, consider multiple communication channels. A phone call or video chat might be more effective than an email for some clients, as it allows for a real-time conversation where issues can be resolved quickly. This also helps build a stronger relationship, as it shows you're willing to take the time to discuss their concerns.

Offering Flexible Payment Options

For customers who can’t pay in full, consider breaking invoices into multiple payments with payment terms moved to a longer timeframe. Set up a credit card facility to give customers other options for payment. After all, the easier you can make it for them to pay you, the quicker you will get paid. If you don’t have payment services set up in your accounting software, we can help you do this. Offering a discount for early payment might provide the incentive for customers who can settle to pay your invoice before others.

In addition to these options, consider setting up automatic payment plans. By allowing customers to pay in smaller, manageable amounts on a regular schedule, you can ensure a more consistent cash flow. This is especially useful for customers facing temporary financial difficulties, as it spreads out the payment burden and makes it easier for them to meet their obligations.

Monitoring Total Outstanding Invoices

Make sure you keep track of how much customers are in arrears. While you can continue to allow credit, you want to make sure you're not creating too much risk. Allowing continual extensions to payment while also letting more to be added to their total amount outstanding can create a cash flow crunch. 

Regularly reviewing your accounts receivable is crucial. By keeping a close eye on which customers are consistently late, you can take early action to address potential issues. Implementing credit limits or requiring partial payment before extending further credit are strategies that can help protect your business from excessive risk.

Get in touch if you want help to better track your cash flow.

Using Automated Reminders

One of the most effective ways to ensure timely payments is by incorporating automated reminders into your accounting software. Automated reminders are a powerful tool that can save you time and ensure that no invoice is forgotten. These reminders can be set to notify customers of upcoming due dates, as well as follow up on overdue payments without you having to remember each one.

Automated reminders can be customised to fit the tone and style of your business, ensuring that they maintain a personal touch. This automation not only helps in keeping the process consistent but also reduces the likelihood of late payments, as it keeps your invoice at the top of the customer's mind. 

If you haven’t yet implemented automated reminders, this could be a valuable addition to your current invoicing process. Our team at First Class Accounts Ovens & Murray can assist you in integrating this feature into your existing accounting software, ensuring you have all the tools you need to manage your accounts efficiently.

Consider a Bill Chaser Service

Managing overdue invoices can be time-consuming and stressful, especially when you're also trying to run your business. That’s where our Bill Chaser service comes in. Designed to take the hassle out of following up on unpaid invoices, this service allows you to focus on what you do best while we handle the rest.

Using our service can help you maintain a professional distance, which is sometimes necessary when dealing with late payments. This can preserve your relationship with the customer, as they may find it easier to discuss payment difficulties with a third party.

Keeping Your Business Financially Healthy

Keeping cash flow going is vital for your business, so the earlier you communicate with customers, the better. 

By being proactive, offering flexible payment options, using automated reminders, and considering services like our Bill Chaser, you can significantly improve your chances of receiving payments on time. Don’t let unpaid invoices become a burden—take steps today to secure your business’s financial health - Contact us.

Successful App Migration

Successful App Migration – A Case Study

Successful App Migration - A Case Study

How ENZED Albury Transitioned from Fishbowl to CIN7 with First Class Accounts Ovens & Murray.

Having the right applications (apps) implemented in your business can significantly enhance efficiency, productivity, and overall operational success. 

Cloud-based apps, in particular, offer unparalleled accessibility and real-time data management, making them invaluable tools. 

Migrating to a more advanced app can address existing system pain points and streamline processes, allowing businesses to operate more smoothly and effectively. 

ENZED Albury recognised these benefits and embarked on a journey to transition their inventory management system from Fishbowl to CIN7, leveraging the expertise of First Class Accounts Ovens & Murray to ensure a seamless migration.

On July 1, ENZED Albury successfully migrated their inventory management system. While the 'go live' date was crucial, the preparation and planning that preceded this transition were key to its success.

Why Move from Fishbowl to CIN7?

ENZED Albury's decision to migrate to CIN7 was driven by the need for a cloud-based solution that could support both their retail store and mobile Hose Doctors. The main advantages of CIN7 included:

  • Anywhere, Anytime Access: This allows staff to review inventory and complete customer invoicing from any location.
  • Seamless Payment Methods: Onsite payments are now more straightforward and efficient.

How First Class Accounts Supported ENZED Albury

First Class Accounts Ovens & Murray played a significant role in ensuring the success of this app migration. Here's how we supported ENZED Albury:

Understanding Pain Points with Fishbowl

We began by identifying the issues with Fishbowl, understanding what wasn't working, and pinpointing areas for improvement. This was essential to ensure that CIN7 would address all of ENZED's needs.

Scoping the Requirements of the New System

We worked closely with ENZED Albury to outline the requirements for their new inventory management system. Key requirements included:

  • Multiple Warehouse Locations: The ability to manage inventory across different locations.
  • Bill of Materials for Assembled Products and Kits: This was crucial for their product management.
  • Integration with Their Barcoding System: Ensuring smooth and efficient inventory tracking.
  • Easy Access for Hose Doctors: Allowing mobile staff to access the system effortlessly.
  • Integration with Xero: Seamless integration with their existing accounting software.

Data Import from Fishbowl to CIN7

We handled the import of all data from Fishbowl to CIN7, ensuring that real-time stock quantities were transferred accurately by June 30.

Training and Support

To ensure a smooth transition, we provided comprehensive training for key staff before the migration. Additionally, we offered support to all staff during the first week of operating with CIN7, addressing any issues and ensuring everyone was comfortable with the new system.

Development of Custom Reports

We developed specific reports to meet ENZED Albury's needs, such as:

  • Hose Doctor Commission Calculations: Ensuring accurate and timely commission payments.
  • Franchise Reporting Requirements: Meeting all reporting needs for franchise operations.

More Than Just Bookkeeping

At First Class Accounts Ovens & Murray, we pride ourselves on offering more than just bookkeeping services. Our mission is to provide comprehensive solutions, including selecting and implementing addon apps that enhance business operations. The successful migration of ENZED Albury to CIN7 is a testament to our commitment to supporting our clients through significant changes.

The Importance of App Migration

App migration, particularly for inventory management systems, can transform the way a business operates. By moving to a cloud-based system like CIN7, businesses can enjoy greater flexibility, efficiency, and accuracy. The benefits of such a transition include:

  • Improved Accessibility: Staff can access the system from anywhere, at any time.
  • Enhanced Efficiency: Streamlined processes and seamless integrations reduce manual work and errors.
  • Better Data Management: Real-time data updates ensure that inventory levels are always accurate.

Could Your Business Benefit from an App Migration?

If you know a business struggling with its current systems or looking to upgrade to a more efficient solution, we can help. Our experience with ENZED Albury's migration to CIN7 shows how a successful app migration can significantly improve business operations.

Get in touch with First Class Accounts Ovens & Murray to discuss how we can support your business in achieving a successful app migration. Whether it's inventory management, accounting software, or other business applications, we are here to help you transition seamlessly and efficiently.

Supercharge Your Business with these ten tips

Supercharge your business

Supercharge Your Business: Proven Strategies for Success

Maintaining momentum and driving growth can be challenging. However, with the right strategies in place, you can supercharge your business and achieve remarkable results. 

Here are ten practical tips to help you navigate each business quarter with purpose, vision, and the courage to elevate your business to new heights.

1. Use Technology

Embrace technology to streamline administrative tasks, enhance communication, and improve reporting and accountability. Utilise the best apps to reduce paperwork and automate processes where possible.

Research and implement software solutions that cater to your specific business needs, such as project management tools, CRM systems, and accounting software. Stay updated with technological advancements and continually seek ways to integrate them into your operations.

At First Class Accounts Ovens & Murray and Busy01 Consulting, we can help your business by integrating the most effective apps tailored to your needs. 

2. Eliminate Distractions

Time is the most precious resource for any business. Many owners find themselves bogged down by distractions and focusing on non-essential tasks. To combat this, be decisive. Reduce standard meeting times, cut down on unnecessary administrative tasks, and delegate whenever possible. By doing so, you'll create more time to focus on what truly matters.

Implementing productivity tools like time-tracking apps can help you identify and eliminate time-wasting activities. Additionally, consider setting specific times for checking emails and notifications to avoid constant interruptions. Creating a daily or weekly priority list can also keep you on track and ensure that you're focusing on high-impact tasks.

3. Say Goodbye to Bad Customers

Some customers may drain your resources without providing significant value in return. If feasible, identify and phase out ten time-wasters, late payers, or troublesome clients. This will not only relieve stress but also allow you to allocate your resources more effectively.

Conduct a customer analysis to identify which clients are profitable and which ones are not. Use metrics such as customer lifetime value (CLV) and customer acquisition cost (CAC) to make informed decisions. By focusing on high-value customers, you can improve your overall profitability and customer satisfaction.

4. Invest More

With the time and mental space gained from the first two steps, allocate resources—time, key personnel, and money—toward strategic initiatives. Passionately redeploy these resources to drive significant improvements in your business.

Consider investing in employee training and development programs to enhance their skills and productivity. Explore opportunities for upgrading your equipment or expanding your product line to meet market demands. These investments can lead to long-term growth and a competitive edge.

5. Get a Plan

Operating without a plan is like embarking on a journey without a map. Develop a robust planning process, create a comprehensive business plan, and ensure its execution.

Include measurable goals and timelines in your plan to track progress effectively. Regularly review and adjust your plan based on market changes and business performance. Incorporate contingency plans to address potential risks and uncertainties.

6. Reconfigure

Don’t let unmotivated or incompatible employees hold you back. If someone isn't a good fit, consider parting ways to free up their future and make room for someone who aligns better with your business goals.

Implement regular performance reviews and provide constructive feedback to help employees improve. Offer opportunities for skill development and career advancement to retain top talent. A positive and motivated team can significantly impact your business success.

7. Value Add

Avoid stagnation by focusing on activities that add value. Aim to make a meaningful impact through your work, ensuring that it brings real value and significance to your clients.

Engage with your customers to understand their needs and preferences. Develop new products or services that address their pain points and exceed their expectations. Consistently delivering value can lead to increased customer loyalty and referrals.

8. Be Different

Stand out from the competition by positioning yourself as unique. Attract ambitious, growing, and engaged clients and employees by breaking the mould.

Identify your unique selling propositions (USPs) and highlight them in your marketing efforts. Foster a culture of innovation and encourage your team to think creatively. Differentiate yourself through exceptional customer service and a strong brand identity.

9. Deploy Marketing

Develop a straightforward marketing plan to enhance your reach and market penetration. Dedicate a percentage of your revenue to marketing efforts and ensure online engagement is a core component.

Leverage digital marketing strategies such as SEO, social media marketing, and email campaigns to reach a broader audience. Monitor and analyse your marketing performance to identify areas for improvement and maximise your return on investment.

10. Ask for Referrals

Actively seek out referral relationships to attract high-quality customers. Networking and word-of-mouth can be powerful tools in driving business growth.

Establish a referral program that rewards customers for referring new clients. Build strong relationships with complementary businesses and explore partnership opportunities. Regularly request feedback from your clients to ensure their satisfaction and encourage referrals.

Supercharge your business

By implementing these ten tips, you can supercharge your business and achieve sustainable growth. Stay focused, be proactive, and continuously seek ways to improve and innovate.

Ready to take your business to the next level? 

At First Class Accounts Ovens & Murray, we provide tailored bookkeeping, payroll and advisory services to help you implement these strategies effectively. Contact us today to learn how we can support your journey to success and supercharge your business!

5 common bookkeeping mistakes (and how to avoid them)

5 common bookkeeping mistakes (and how to avoid them)

5 common bookkeeping mistakes (and how to avoid them)

Are you making any of these common bookkeeping mistakes? Starting a business can be a challenging experience, especially when it comes to managing your numbers and staying on top of your financial management.

Unless you’ve got some experience in finance, the bookkeeping and accounting requirements can be quite daunting. And even with today’s helpful cloud accounting platforms and fintech apps, there’s always the possibility of making a simple accounting mistake.

So, what are the most common bookkeeping mistakes made by business owners? And what can you do to avoid these pitfalls and keep your finances looking healthy and shipshape?

The top five mistakes to avoid

‘Doing the books’ is unlikely to be your favourite part of running a small business. But the better your accounting and bookkeeping know-how and skills, the more oversight you have over the financial path (and future success) of your company. It really is that simple.

But there are plenty of traps that a newbie owner can fall into – and even a few hurdles that the more experienced business owner may trip over from time to time.

Let’s take a look at the five most common bookkeeping mistakes.

1. Mixing your personal and business finances

When you don’t separate your personal and business transactions, this blurs the lines and makes it difficult to track your income and expenses accurately. It can also lead to personal spending being counted as business deductions, causing tax issues later on.

Solution: Open separate business and personal bank accounts and keep them entirely separate and distinct.

2. Skipping the record-keeping process

If you fail to keep receipts, log your invoices and keep proper records this can be a major problem further down the road. Detailed records are crucial for tax filing, budgeting and identifying spending trends.

Solution: Keep digital copies of all receipts and be sure to keep your bookkeeping up to date and well-managed.

3. Miscategorising your expenses

Throwing all your expenses under ‘miscellaneous’ makes it far harder to analyse your spending and cashflow. With every item of expenditure logged under a specific code from your Chart of Accounts, you can quickly run reports, review your spending and look at ways to improve budgets and cashflow.

Solution: Categorise your expenses properly (rent, marketing, supplies etc.) to understand where your money goes.

4. Winging it when filing your taxes

Taxation is complicated and it’s easy to make costly mistakes if you’re not prepared and organised. Don't wait until tax season to sort everything out and make sure you’re aware of all your business tax liabilities.

Solution: Set aside funds for taxes throughout the year, and consider consulting an accountant or tax adviser to ensure you're filing correctly and taking advantage of all potential government deductions and tax incentives.

5. Failing to get proper accounting advice

If managing your finances becomes overwhelming, don't be a hero. Cloud accounting software can automate some of the key tasks, and a bookkeeper can handle day-to-day record-keeping.

Solution: Think about outsourcing and partnering with an experienced accounting firm to get real peace of mind and improved financial management.

Talk to us about outsourcing your key bookkeeping tasks.

You didn’t start your business to spend hours working on your bookkeeping and accounts. Why not outsource your key bookkeeping and tasks to us, and put those hours back into your business.

As your bookkeeping partner, we can:

  • Show you how to clearly separate your personal and business finances
  • Set up your bookkeeping to be as streamlined, automated and efficient as possible
  • Show you the best software tools and processes for managing your expenses
  • Become your BAS agent 
  • Provide reporting, management information and advice to guide your decision-making

Get in touch to talk about outsourcing your finance tasks

How Much Should You Charge?

How much should you charge

How Much Should You Charge?

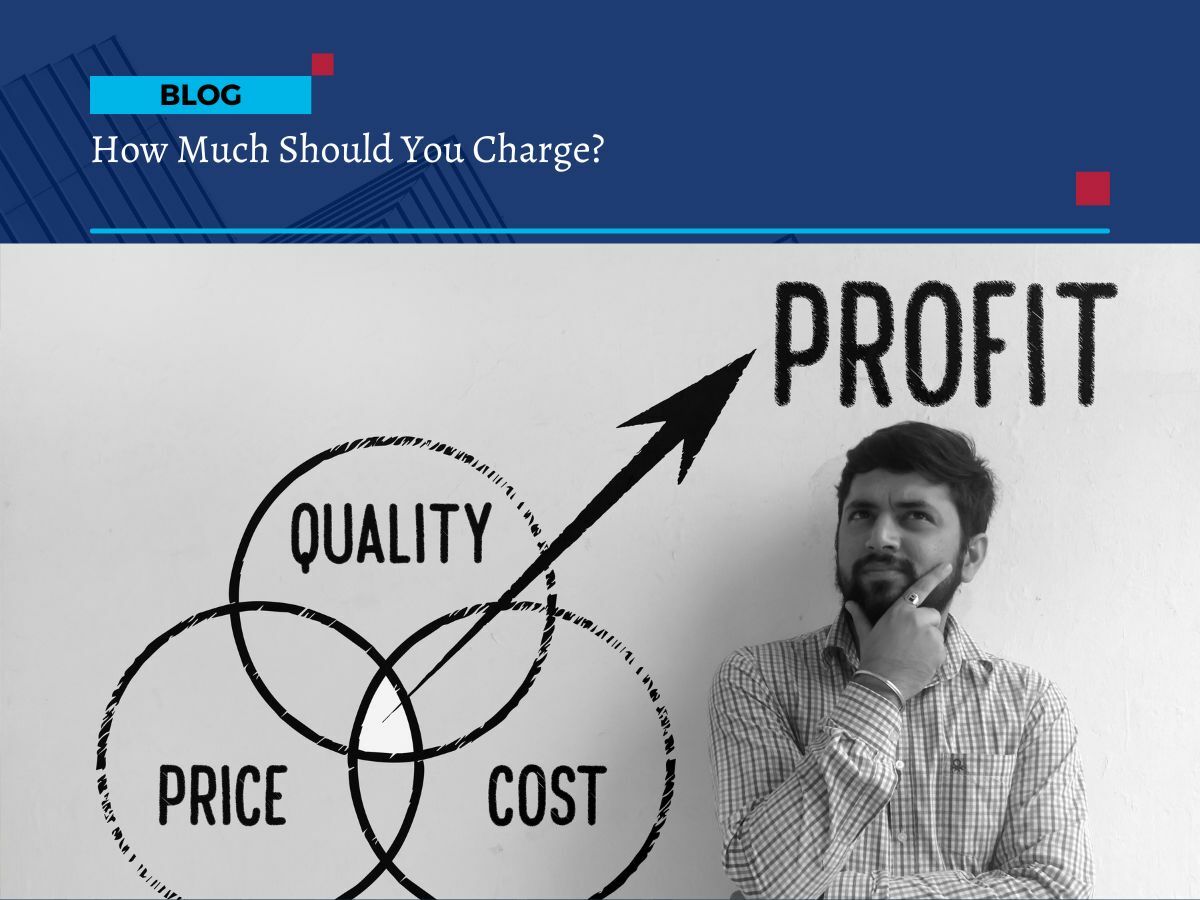
Getting your pricing right is one of the best ways to plan for business success, but how do you know how much you should charge?

First, don’t make a rushed decision; take the time to properly understand the market, your total costs, and how to position your products or services.

Figuring out how much to charge is a big learning curve for any business owner. The answer to how to approach it will fluctuate as circumstances and markets change. It is important to revisit the question throughout the lifecycle of your business.

There is No Magic Formula

All businesses are unique, with an individual offering of products and services. Before you set your pricing, it’s important to look at the whole picture. This will help to ensure you are being strategic and not just following trends.

Gather the Data

To get started, you need to gather as much information as possible. Block out some time to sit down with your business data and strategies. Pricing is essentially figuring out where your products and services are positioned in the market. So keep your business strategies top of mind. It doesn’t have to be a confusing exercise. Just grab a coffee and get started.

Here Are the First Steps to Consider:

1. Record All the Costs Involved in Production

Start by listing all direct and indirect costs associated with your product or service. Direct costs include materials, labour, and production expenses. Indirect costs encompass assets, insurance, licences, and legal fees. This comprehensive list ensures you don't overlook any expenses that could affect your pricing strategy.

2. Consider Your Current Profit Margin or Required Margin

Once you have your total costs, think about your profit margin. Understand the difference between net and gross profit margins. Gross profit margin is the difference between sales and the cost of goods sold, while net profit margin accounts for all operating expenses. Decide what margin is necessary for your business to be sustainable and profitable.

3. Conduct Thorough Competitor Research

Research your competitors thoroughly. Understand the market landscape and what others are charging for similar products or services. Identify your unique selling points (USPs) that allow you to differentiate your pricing. This research helps you position your offerings competitively without underpricing or overpricing.

4. Evaluate Your Offerings

Assess the value-added aspects of your products or services. Consider where your offerings fall on the spectrum from cheap and no-frills to high-end premium. Can you create a range of products at different price points to cater to various segments of the market? This strategy can help you attract a broader customer base.

Revisit and Adjust Your Pricing Regularly

Market conditions and business circumstances are always changing. Regularly reviewing and adjusting your pricing ensures that you stay competitive and meet your customers' expectations. This proactive approach helps you maintain profitability and growth.

Additional Considerations

Understanding Customer Perception

How customers perceive your pricing can significantly impact your sales. If your prices are too low, customers might question the quality of your products. Conversely, if your prices are too high without justifiable reasons, you might drive potential customers away. Balancing perception with reality is key to effective pricing.

Value-Based Pricing

Value-based pricing involves setting prices based on the perceived value to the customer rather than the cost of production. This method requires a deep understanding of your customers' needs and how much they are willing to pay for the benefits your product or service provides. Value-based pricing can often lead to higher profit margins.

Psychological Pricing

Psychological pricing strategies, such as setting prices just below a round number (e.g., $9.99 instead of $10), can influence customers' buying decisions. This tactic can make prices seem lower than they actually are, potentially increasing sales.

Discounts and Promotions

Strategically use discounts and promotions to attract customers and boost sales. However, be careful not to rely too heavily on these tactics, as they can devalue your product and create an expectation for lower prices. Use them sparingly and strategically to drive short-term sales and customer acquisition.

Stay Ahead of the Game

Determining how much to charge for your products or services is a crucial aspect of running a successful business. By thoroughly understanding your costs, profit margins, market conditions, and customer perceptions, you can develop a pricing strategy that supports your business goals. Remember, pricing is not a one-time decision but an ongoing process that requires regular review and adjustment.

For more personalised assistance in developing a pricing strategy tailored to your business needs, contact us at First Class Accounts Ovens & Murray and Busy01 Consulting. We're here to help you navigate the complexities of pricing and achieve long-term business success.

Business Strategy

Get strategy at the heart of your successful business

Get strategy at the heart of your successful business


Putting strategy at the heart of your business activity should give you greater direction and focus and lead to stimulating, profitable opportunities. A well-thought-out strategy is crucial for navigating challenges and capitalising on opportunities.

Businesses that have clear objectives or goals, robust accountability, and a shared sense of purpose should always outperform those that just show up and go through the motions. This focused approach ensures that all efforts are aligned towards achieving common goals, thereby maximising efficiency and effectiveness.

The Importance of a Strategic Plan

Strategy lies at the heart of most successful businesses. 

To achieve this, you need to resource and execute with purpose. Unfortunately, few businesses have a strategic plan or a robust planning process. 

Changing this situation should be a top priority. A strategic plan not only provides a roadmap for your business but also helps in anticipating challenges and preparing for them.

Business Strategy Tips for Business Owners

To help you get started, here are two top tips for putting strategy at the heart of your business success.

1. Process Creates the Plan

Getting strategy at the heart of your success will require you to carve out some time, get a process started, and shake things up. There’s no better time to review and tweak your business model, future-proof compelling services, and get your strategic building blocks in place.

Just as every good strategy has key elements, every good plan needs a step-by-step process. In fact, the process is often just as important as the plan itself. 

A strategic planning retreat with your core team is a great way to start the process – find a spot offsite to get the creative juices flowing such as a beach, a park, or a vineyard, and set an agenda.

2. Key Elements of an Effective Strategy

The key elements in a good strategy normally incorporate:

  • Vision: This is a statement that identifies what a company would like to achieve or accomplish. A clear vision provides direction and inspiration, helping to align all members of the organisation towards common goals.

  • Values: These are the fundamental beliefs upon which your business and its behaviour are based. They are the guiding principles that your business uses to manage its internal affairs as well as its relationship with customers. Strong values build a solid foundation for organisational culture and decision-making.

  • Objectives: These should be SMART (specific, measurable, achievable, realistic, and timebound). Having both short-term and long-term objectives ensures that your business stays on track and can measure its progress effectively.

  • KPIs: Key Performance Indicators are measurable values that demonstrate how effectively a company is achieving key business objectives. KPIs help in monitoring performance and making informed decisions.

  • Actions: These outline what needs to be done to meet the objectives. Make this simple and clear to ensure that all team members understand their roles and responsibilities.

  • Owners: Delegating tasks to specific owners ensures follow-through and accountability. Assigning ownership of tasks helps in tracking progress and maintaining responsibility.

  • Deadlines: Setting deadlines for when your actions will be complete ensures you make progress. Deadlines provide a sense of urgency and help in prioritising tasks.

It doesn’t need to be much more complicated than that, but do invest the time and effort in doing this right. 

A proactive, value-add strategic model will need fresh thinking, debate, research, and open conversations. Enjoy and embrace the process, and you should end up with a good outcome.

Implementing Your Strategy

Implementing a strategic plan requires commitment and consistent effort. Here are some additional steps to ensure successful implementation:

  • Communication: Clearly communicate the strategy to all members of the organisation. Ensure everyone understands their role in achieving the strategic objectives.

  • Monitoring and Evaluation: Regularly monitor progress against the set objectives and KPIs. Evaluate the effectiveness of your strategy and make adjustments as necessary.

  • Flexibility: Be prepared to adapt your strategy in response to changes in the business environment. Flexibility is key to maintaining relevance and achieving long-term success.

  • Continuous Improvement: Foster a culture of continuous improvement within your organisation. Encourage feedback and use it to refine your strategy and processes.

Seeking Professional Guidance

Great planning requires a guide, facilitator, and/or professional expertise to be as robust as possible. We can help your business and guide you through the steps. Professional guidance can provide valuable insights and ensure that your strategic plan is comprehensive and effective.

Putting strategy at the heart of your business activity should not only give your business greater direction and focus but also lead to stimulating, profitable opportunities. 

It’s time to get started on creating a strategic plan that will drive your business towards long-term success. By following these steps and seeking professional assistance when needed, you can build a solid foundation for your business and achieve your strategic goals.

Talk to us about how we can support your business strategy and help you achieve your objectives. 

Remote work in 2024

Remote work in 2024

Remote Work in 2024: Adapting to the New Normal


Remote work has significantly evolved over the past five years, becoming a mainstay for many businesses.

Back in 2019, we discussed the rising trend of remote work in our blog "Remote Work is on the Rise". As we move further into 2024, it’s clear that remote work is no longer a temporary solution but a permanent fixture in the way we operate.

The benefits of remote work in 2024

Attracting and Retaining Talent

Remote work opens the door to a global talent pool. You're no longer restricted to hiring within your local area or requiring employees to relocate. This flexibility is a major draw for top talent who value work-life balance.

Increased Productivity

Many studies have shown that remote workers often achieve higher productivity levels than their in-office counterparts.

For example, a study by Great Place to Work found that remote work increased productivity by 13% during the pandemic (Great Place To Work®). Additionally, research from McKinsey indicated that flexible working arrangements have significantly boosted employee satisfaction and productivity (McKinsey & Company).

Cost Savings: Both employers and employees can save money. Businesses can reduce overhead costs related to maintaining physical office spaces, while employees save on commuting expenses. According to Business News Daily, remote workers also experience less stress, contributing to increased productivity (Business News Daily).

The Benefits of Outsourcing Bookkeeping and Payroll to Remote-Capable Organisations


Outsourcing bookkeeping and payroll to firms that excel in remote work, like Busy01 Consulting and First Class Accounts Ovens & Murray, offers several advantages:

Consistency

Services are unaffected by location or employee absences. With remote teams, firms like Busy01 and FCA ensure that your bookkeeping and payroll tasks are completed on time, every time.

Expertise

Access to a team of experts who are well-versed in the latest technologies and best practices, ensuring compliance and efficiency.

Focus on Core Activities

As a business, you can focus on your core competencies while leaving the complex and time-consuming tasks of bookkeeping and payroll to professionals.

Scalability

Easily scale services up or down depending on your business needs without the hassle of hiring and training new staff.

Security and Data Protection

With the increase in remote work, data security has become a top priority. Businesses must ensure that their remote work policies include robust cybersecurity measures. This includes using VPNs, secure cloud services, and regular training on data protection practices.

At Busy01 and First Class Accounts (FCA), we emphasise the importance of maintaining high security standards to protect sensitive business data. For more detailed information on cyber security, you can refer to our blog, here.

Preparing Your Business for Remote Work in 2024

Establish Clear Communication Channels

Strong communication is vital for remote teams. Ensure you have multiple channels for different types of communication:

  • Instant Messaging: Tools like Slack for quick, informal communication.
  • Video Conferencing: Regular video calls via platforms like Zoom to maintain face-to-face interaction.
  • Project Management: Software like Trello or Asana to keep track of tasks and deadlines.

Invest in Technology

Provide your remote employees with the necessary technology:

  • Hardware: Laptops, monitors, and other required devices.
  • Software: Subscriptions to essential tools and applications.
  • Support: Technical support to assist with any issues that arise.

Foster a Positive Remote Work Culture

Building and maintaining a positive work culture is crucial. Encourage regular team-building activities, virtual social events, and ensure managers are trained to support remote employees effectively.

Address Tax and Legal Considerations

Remote work can have tax implications. Make sure you are aware of the regulations in your area and seek advice to ensure compliance. This includes understanding how remote work affects payroll, benefits, and other legal aspects.

Embrace the Future of Work

Remote work in 2024 is more refined and ingrained in our work culture than ever before. By focusing on robust communication, mental health, security, and the right technology, businesses can thrive in this remote-first world.

If you’re considering or expanding remote work for your team, contact us to ensure your systems are up to date and you’re compliant with all necessary regulations.

1 … 11 12 13 14 15 … 34