Renae Pitargue, Author at First Class Accounts Ovens and Murray and Busy01 Consulting - Page 21 of 34

All Posts by Renae Pitargue

Digital Signatures and Cyber Security

Digital Signatures and Cyber Security

Digital Signatures and Cyber Security

Authenticated digital signatures can be a valuable part of your cyber security approach. They are more efficient than printing, signing and scanning documents and provide one-off encryption for the highest level of security. In fact, they are more secure than a handwritten signature.

If you have a lot of documents that require signing within your business, whether internally or externally, using a digital signature app will streamline your workflow and make managing the signing of documents more accessible. Documents are also secured against manipulation after they have been signed.

However, not all digital signatures have the same level of verification and cyber safety.

Digital signatures vs Electronic signatures

It's important to understand the difference between electronic and secure digital signatures.

For example, you can scan your signature, save it as an image file, and attach it to documents. This is an electronic signature but not an authenticated digital signature and is easily copied and hacked.

An authenticated signature includes unique digital verification that uses public key cryptography technology within the signature. So, the signature comes with encrypted authorisation embedded in it, and it’s virtually impossible to hack.

Digital signature process

Digital signatures also provide an audit trail of the signature process – from sending the document to when it's read and signed, and sent back to the document owner.

Once you’ve created a document and sent it for signing, you can see outstanding documents at a glance and send reminders from within the platform.

There are many options available for authenticated digital signatures. Look at DocuSign, Adobe or Secured Signing to start with and ask others in your industry if they use a solution they would recommend.

Check their level of encrypted security and audit trail functions. Most are very simple to use, requiring nothing more than you opening an account, uploading documents and sending. The recipient may need to create an account, but some apps use a code sent separately to sign the document without the recipient needing their own account.

Digital signatures are an easy tool to help your business's cyber safety, and there are many other simple tips you can implement. Talk to us if you’d like to learn more about how your business can stay cyber-safe and secure.
Business plant and equipment: Buy or lease?

Business plant and equipment: Buy or lease?

Business plant and equipment: Buy or lease?

When your business needs new plant or equipment, what’s the best choice – buy or lease? The answer will depend on your specific circumstances, but there are some basic considerations that can help you weigh up the options.

The advantages of buying

Buying gives you certainty and ownership, at a higher upfront price, but a lower total price. Owning an item of plant or equipment gives you unrestricted use for the lifetime of the item. You can alter it to suit your business, and you can sell it if you need to free up some cash. The full cost is paid up front, so you have no ongoing payments, and there may be opportunities for tax depreciation.

When equipment lasts for a long time and maintains its value, ownership can be a particularly good choice. Overall, the total price of ownership is usually lower than the total cost of leasing the item.

The advantages of leasing

Leasing tends to give you more flexibility, at a higher cost. It spreads out the cost of an expensive item – you don’t need to save or borrow the purchase price, and instead you make regular payments. You can return a leased item if it’s not working out, or upgrade to a better model as your business grows.

If the equipment or plant is something that quickly becomes obsolete, or that you’re likely to upgrade, or that you’re not totally certain is right for your business, leasing could be ideal. While leasing is generally more expensive across the lifetime of the item, it also frees up your money to invest in other areas of the business.

Running the numbers can help you find the right decision

The decision to invest in new plant or equipment can be a tricky one, but we can help.

We can tally up the upfront and ongoing costs, and weigh these against the economic benefits you might get from the new equipment. We consider your cashflow, the cost of borrowing, and sales projections, so you can make an informed choice.

Drop us an email or give us a call – we’re here to help.

New accountability measures proposed for ABN holders

New accountability measures proposed for ABN holders

New accountability measures proposed for ABN holders

Originally announced in the 2018–19 Federal Budget, and now set out in draft legislation, are newly introduced accountability measures for ABN holders.

Once in effect, this will mean you will have to:

  • lodge outstanding income tax returns, and
  • confirm the accuracy of your entity's details on the Australian Business Registrar annually.

Currently, there are no registration penalties for ABN holders when it comes to lodging tax returns. That is, you can continue to quote an ABN regardless of whether you have lodged outstanding returns.

The regulator will now have the ability to cancel your ABN if you have 2 or more outstanding income tax returns for income years commencing on or after 1 July 2022. Also, the regulator will be able to cancel your ABN if you do not confirm the accuracy of your ABN details in an annual form on or after 1 July 2024.

If your ABN gets cancelled by one of these measures, the registrar must reinstate your ABN once the outstanding items have been resolved.

We are closely monitoring the progression of this draft legislation and once further information is provided by the Treasury, we will inform you of the specifics surrounding the legislation.

Improve your financial stability

Improve your financial stability

Improve your financial stability

We know that building long-term relationships with your customers makes good sense for your customer experience. But good relationships are also a key factor in making your business more financially stable and improving your bottom line.

The answer lies in nurturing the relationship, building a sense of trust and satisfaction that leads to regular sales and a boost to your revenue.

Nurturing customer relationships that drive your profits

A business with no customers has no future. But a business with a pipeline of happy, satisfied customers can rest assured that it has a more stable and successful future ahead of it.

This network of happy customers doesn’t appear overnight. It takes time. But once you’ve built these foundations, you’ll begin to see the financial and non-financial benefits.

To drive your financial stability through customer relationships, you’ll need to:

Build trusted relationship with your customers

Having strong relationships with customers helps to create loyalty. If you can succeed in building this feeling of trust between both parties, you’re onto a winner – and can rest assured that you have a receptive audience who will want to buy your products and services.

Aim for repeat business and increased sales

A trusted customer relationship can lead to repeat business. As the old saying goes, you only have one chance to make a first impression. But if you continue to make a good impression, time after time, sale after sale then your customers will come back for more.

Turn your customers into brand advocates

Customers that see the value in your proposition, and repeatedly buy from your brand, become advocates for your brand. They’ll tell their friends, their colleagues and others in their network just how great you are – and that’s the best kind of advertising a company can buy. This leads to referrals and word-of-mouth promotion, creating another channel for enquiries and sales.

Learn from your customers

Deeper relationships also help you understand your customers’ needs in a broad and detailed way. Talk to your satisfied customers, listen to their feedback and use this information to develop and build products or services that truly meet their needs and expectations.

Keep the business competitive and agile

Closer customer relationships help you stay competitive in your industry by offering solutions that cater specifically to your target audience. If there’s a significant change in your customers’ needs, or a seismic shift in the market, you can pivot, diversify and take the business in a new direction.

Keep the cash rolling in

A satisfied customer base will spend more readily and will also spend more. These benefits deliver a more predictable level of sales – a huge advantage for any business. Predictable sales = stable revenue + positive cashflow. And that’s excellent news for your financial health and your end profits.

This means:

  • You can accurately predict your income over a given period
  • You can easily cover your operational expenses and ad hoc costs
  • You have money to invest back into the business for development or growth
  • You have better end-of-period profits, keeping you and your investors happy.

Talk to us about improving the financial stability of your business

Long-standing, evolving and trusted relationships with customers are the bedrock of your business. If you get it right, these solid relationships can result in increased sales, income and profits – all of which keeps the business more financially stable.

If you want to know more about nurturing customer relationships, and how you can tie this into your financial stability, please book in some time for a chat.

5 ways to get in control of your business finances

5 ways to get in control of your business finances

5 ways to get in control of your business finances

Having proper control of your business finances is a big advantage. It helps you make well-informed business decisions and keeps your organisation profitable.

With so many digital tools for managing your bookkeeping, accounting and management reporting, it's never been easier to manage, track and forecast your financial position.

But what are the main tools you need? And how do you set up your financial systems, apps, processes and reporting to put yourself back in the finance driving seat?

1. Bring your bookkeeping into the digital age

Digital bookkeeping apps are a great way to digitise your receipts, records and source documents. This not only saves a lot of time at year-end, it also makes it much easier for you to keep track of your company’s finances and accounting. Keeping your receipts in a box to manually enter at period-end is no longer enough. Take the next step and digitise your receipts at source, so you have up-to-date digital records and copies of source documents.

Optical character recognition (OCR) software, like Dext Prepare or Auto Entry, scans the receipt, converts it into a digital format and stores it in the cloud.

2. Do your accounting in the cloud

Cloud accounting is a software-as-a-service (SaaS) solution that helps you carry out all your main accounting and financial management online, without having to install any software.

Cloud accounting providers, like Xero, QuickBooks, MYOB or Sage, design their accounting platforms to take the pain and hassle of business accounting. You get all the tools and features you need to work on your accounting tasks. And your platform provider will also take care of all the data storage, backups and security of your data.

A good cloud accounting platform does more than just save your hard drive space. It also provides you with tools and dashboards that improve your access to management information, financial reporting, forecasting and projections, performance tracking and more.

3. Use the latest in expense management tools

Expense management can be a time-consuming and tedious job. But it’s also a vital task that helps you ensure you’re spending company money wisely and not overspending. If employees start going over their budget limits, this can be a costly mistake for the company and your cashflow.

Expense management tools, such as Soldo, Weel or Pleo, help you manage staff spending by giving employees virtual cards that are linked to a specific budget, account and code. This helps you track their expenses easily and make sure they’re staying within their budgeted limits. These platforms also give you detailed reporting and analytics, so you can see where money is being spent, and where savings can be made.

4. Make it easy to accept digital payments

The problem of slow payment is one of the most frustrating things for small businesses. If your customers don’t pay on time, this can result in a loss of revenue, poor cashflow and an inability to cover your basic costs and overheads. To resolve this issue, many companies have begun to switch to digital payment platforms that make it simpler, faster and easier to collect payment.

Payment platforms, like PayPal, Square or Stripe offer faster payment times and more control over the customer experience. Some platforms even integrate with your cloud accounting, so you get automatic bank reconciliations.

5. Embrace the latest in digital reporting and forecasting

With digital accounting changing so rapidly in recent years, there's never been a better time to embrace the benefits of the latest in digital reporting and forecasting.

Economic conditions are hard to predict. So it's crucial to be able to quickly analyse data, check your performance and make predictions about how your company will fare in the coming months. When you use cloud solutions for financial reporting and key metrics, you'll be able to monitor trends in real-time while having access to the data anytime, anywhere.

Having this information at your fingertips helps you make informed decisions faster than ever before – and that translates that into more sales, increased business growth and bigger profits.

If you’re looking to give your finances a touch of digital magic, please do come and talk to us.

We can walk you through the best cloud platforms, fintech apps and business tools to add to your app stack – so you’re ready to make the most of a digital approach to your finances,

Paid family and domestic violence leave

Paid Family and Domestic Violence Leave – New Entitlement Rules

Paid Family and Domestic Violence Leave

New Entitlement Rules

Employees of non-small business employers can now access 10 days of paid family and domestic violence leave in a 12-month period.

Employees of small businesses can access the leave from 1 August 2023.

Employees have had an entitlement to unpaid family and domestic violence leave (FDVL) for some time as part of the National Employment Standards (NES). But as of 1st February this is a paid leave entitlement for employees of larger employers and 1 August 2023 for employees of small employers (fewer than 15 employees).

The new law allows ten days of paid leave every 12 months, but the leave does not roll over and accumulate.

The full pay rate will apply as if the employee had worked as usual on the day of the leave.

The new FDVL means employees can take time off to deal with the impacts of domestic violence or abuse if they need to take care of things during working hours. This includes attending court, accessing police or support services, or making arrangements for the safety of oneself or close relatives.

FDV Leave Eligibility and Proof
  • Applies to all employees, permanent and casual.
  • Close relatives include a spouse, partner, former partner, child, grandchild, parent, grandparent or sibling; or the child, parent, grandparent, grandchild or sibling of a current or former spouse or partner. Torres Strait Islander and Aboriginal kinship relatives are also included.
  • The leave is available as soon as an employee starts with an employer.
  • Employees must inform the employer as soon as possible about the need for FDVL and the expected length of leave.
  • The employer can ask for evidence such as police, court, or support service documents, or a statutory declaration, even if the leave period is less than a day.
Plan for Increased Payroll Costs

Because the new leave provision applies from day one of employment for all employees, employers should plan for the potential cost of the leave.

While it's unlikely that all employees will take this leave, preparing for the possible cost means you won't get caught out if you do have to pay FDV leave, particularly for casual workers.

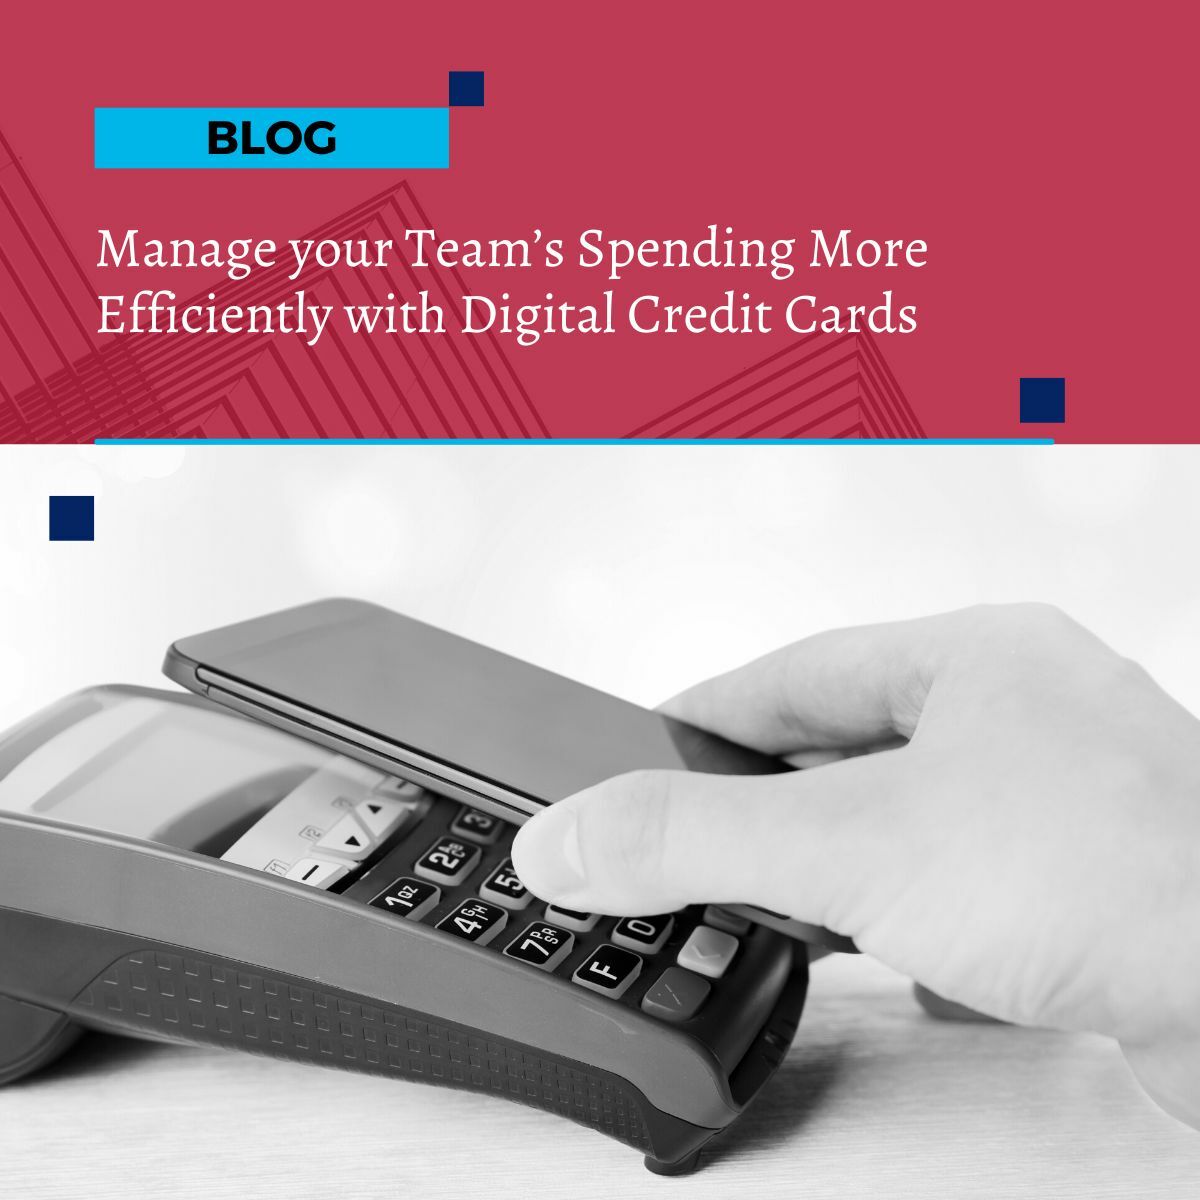
Manage your Teams Spending

Manage your Team’s Spending More Efficiently with Digital Credit Cards

Manage your Team’s Spending More Efficiently with Digital Credit Cards

Do you need to manage expenses for your business and team? Digital credit cards have been around for some years but have recently grown in popularity as their user-friendly practicality is becoming appreciated by many business owners.

How do Digital Credit Cards Work?

The provider issues a digital card number in exactly the same format as a regular credit card. Cards are assigned to individuals who can use the card for all expenses, such as automatic credit payments for subscriptions or buying business purchases in-store using their Android or Apple wallet.

The cards are linked to the business bank account, which means the owner can control the amount of money allocated to a particular card. Within each card, you can set limits according to budgets for different types of spending categories or projects, and you can always see exactly how much of the set budget a team or individual staff member has spent.

Staff can request additional funds if needed, and you can customise limits and authority levels for each user. Managing expenses becomes far more efficient and structured rather than relying on expense reports submitted long after the expense has been incurred.

Digital credit cards are easy to activate and, in some cases, are virtually immediate. You'll get a dashboard by the provider that lets you see real-time information about where your money is being spent and by whom.

Using the card on a smartphone means a photo of the invoice or receipt can be uploaded immediately, making business bookkeeping more effective and accurate as data is captured at the time of the expense.

There are many providers of digital cards, and we encourage you to research the options, but if you need to manage team expenses, getting some form of digital card will be well worth your while.

Apart from the improved control and efficiency digital cards give the business owner, one of the most significant benefits is the minimisation of fraud and unapproved automatic billing.

Talk to us if you'd like to understand more or if we can help integrate the digital cards into your accounting software file.


Secure Jobs and Better Pay Bill

Secure Jobs and Better Pay Bill – How will it affect your business?

Secure Jobs and Better Pay Bill - How will it affect your business?

The Secure Jobs and Better Pay Bill 2022 was passed in November 2022 as an amendment to the Fair Work Act 2009.

Some changes start immediately, and others will roll out over the next six months to a year.

The act amends workplace relations laws relating to many aspects of employment. While not every new law will affect every employer, it's essential to understand the extensive changes that are coming.

The Main Changes

  • Flexibility of working hours, enabling workers to negotiate hours that suit them.
  • Collective enterprise bargaining allows employers within the same industries to negotiate common pay and conditions agreements.
  • Changes to the enterprise bargaining system to make it easier for employees to initiate bargaining for an enterprise agreement where existing enterprise agreements have expired.
  • Fixed term contract limitations will constrain the number of times a contract can be renewed. This should result in employers offering permanent positions to workers once the contracts have ended.
  • Pay secrecy clauses in employment agreements must be removed, meaning an employer cannot force an employee to keep from discussing their pay with colleagues.
  • The right to protection from sexual harassment means employers must be proactive in fostering an environment free from sexual harassment.
  • Changes to the better off overall test (BOOT) should make assessing whether a proposed agreement passes the test simpler.
    Equal remuneration principles to promote gender pay equality.

What Next?

The Bill has brought significant reforms to employee entitlements that make it more important than ever to ensure your employment agreements comply with the new laws.

There will be more updates next year about the changes, but in the meantime, we recommend you prepare for the new laws that will affect your business.

Get in control of cashflow

Get in control of cashflow


Get in control of cashflow

It's an undeniable fact - cashflow is the lifeblood of any business. Without enough liquid funds coming in, it becomes harder to do the basics like trading and paying suppliers. Even worse, a lack of cash can eventually lead to failure for a business. That's why effective cashflow management is so important.

No one likes to think about potential financial disasters, but being proactive with your cashflow can make all the difference when it comes to keeping your business afloat. You need to understand not only where your money is going, but also how you can put yourself in a positive cashflow position so you have enough on hand to cover your expenses.

Fast ways to improve your cashflow

Managing your cash flow is an ongoing process.

Keeping close tabs on the numbers in your regular cash flow statements is key. A negative drawdown could be caused by insufficient sales, unpaid invoices, or not controlling costs effectively.

What's important is to take a complete approach and proactively find ways to improve your company's cash situation.

Some key ways to boost your cash position include:
Make it Easy to Get Paid – Using the Latest in Payment Tech to Speed up Payment Times

Getting paid quickly is essential for maintaining a healthy cash flow. The faster you receive payments from customers, the better off your business will be financially.

To make this happen more effectively, you should use modern payment technologies such as online invoicing software or mobile payment apps that allow customers to pay quickly and securely via their smartphones or computers. This will reduce late payments significantly and give your cash position a boost.

Track and Manage Debts – Chasing Any Late Payments To Reduce Your Aged Debt

Another way of improving your cash position is by tracking any outstanding payments due from customers so that you can start chasing them up promptly if they are late in paying their invoices.

Look into setting up automated reminder systems so that customers are sent reminders when they are overdue on payments. This will help reduce the amount of aged debt in your books which can have an impact on your bottom line.

Manage Spending Effectively – And Start Tracking Reviewing And Reducing Your Costs

There’s no point increasing income if it’s all going out again on unnecessary costs.

It’s important to keep track of where every dollar is going each month so that you can identify any areas where money may be being wasted unnecessarily. Once these areas have been identified, then steps can be taken to reduce these costs so that they don't eat away at any additional profits made by increasing sales or reducing aged debt levels.

Improve Your Sales and Marketing – Creating More Sales and Boosting Income

One of the best ways to increase your cash position is by boosting your sales revenue.

To do this, you need to make sure that your marketing efforts are effective at generating leads and converting them into customers. This means investing in the right marketing strategies such as website design, search engine optimization (SEO), content marketing, social media marketing, email campaigns, etc. You could also consider offering discounts or promotions to encourage customers to purchase from you more regularly.

Talk to us about improving your cashflow.

If cashflow is becoming a headache for your business, we can help you with cashflow forecasting and understanding your cash position to support you attaining that all-important positive cashflow position.

Get in touch to improve your cashflow.

1 … 19 20 21 22 23 … 34